|
The Week Ahead: Highlights
US Preview
Markets Eye 25 BP Rate Move from FOMC
By Theresa Sheehan, Econoday Economist
The focus of the September 14 week will be the FOMC meeting
on Tuesday and Wednesday. The tone of the Beige Book released on September 2,
the benign monthly employment report for August, and the unfavorable inflation
data in the August reports for final-demand producer and consumer prices leave
little doubt that the risks to the outlook fall firmly on the side of price
stability. Add to that the increased geopolitical instability of recent weeks
as the Trump administration ramps up attacks on Iran and picks a trade fight
with the USs biggest trading partner -- Canada. Between higher energy costs,
disruptions to supply chains that will result in higher prices for businesses
and consumers, future inflation reports are not likely to show improvement.
This will also push inflation expectations for the medium term back up.
Fed Chair Kevin Warsh has been emphatic about the FOMCs
commitment to bringing inflation down and that the Feds primary tool is
setting the fed funds target rate. As such, the FOMC will have little choice
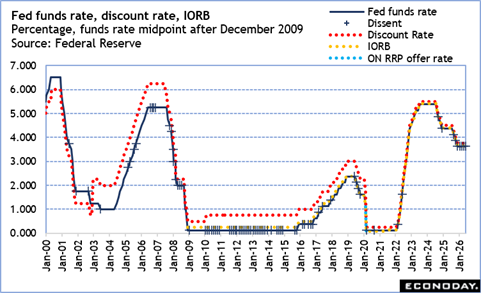
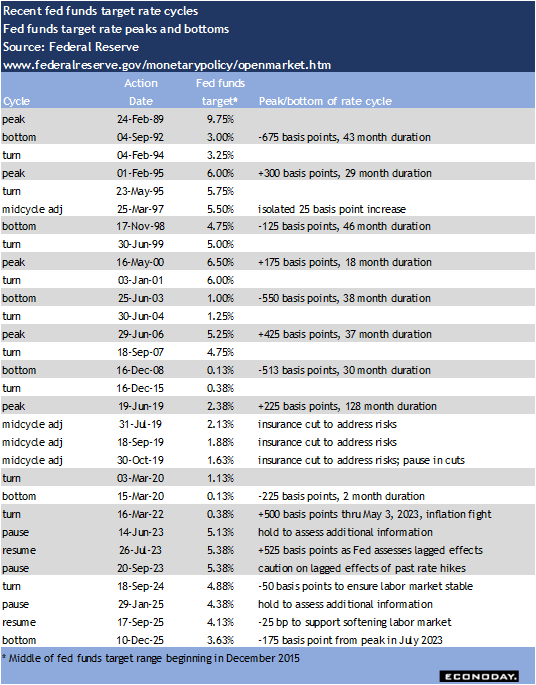
but to increase the fed funds target rate range from the 3.50-3.75 percent that
has been in place since December 2025. However much the committee may view the
present circumstances as likely to be of limited duration, that duration is
lengthening and of uncertain resolution. The potential for inflation to become
entrenched is worsening. Moreover, higher prices are going to stick for many
goods and services even if prices at the gas pump fall.
The FOMC announcement is set for 14:00 ET on Wednesday. The
most likely hike is 25 basis points. It could well be labeled a mid-cycle
adjustment to indicate that once the tit-for-tat tariff battle with Canada ends
and a lasting negotiated settlement with Iran is in place a more distant
prospect that interest rate cuts will be on the table again.
If there is no change in rates, the three district bank
presidents who dissented in the July 29 vote probably will dissent again. These
were Clevelands Beth Hammack, Minneapoliss Neel Kashkari, and Dallas Lorie
Logan. It is not impossible that an addition dissent or two could be
registered. Any dissents will reflect concern that the FOMC is behind the curve
on addressing inflation and maintaining its credibility as an inflation
fighter.
The September meeting is one at which a summary of economic
projections (SEP) is routinely prepared. Warsh abstained from the prior one and
will do so again for this one.
Warsh is scheduled to speak with the press at 14:30 ET on
Wednesday. When it comes to the FOMC deliberations, expect Warsh to
characterize it as a healthy family fight around the table to reach a
decision. Also expect another round of questioning to get a solid hint of the
next steps in monetary policy which Warsh will sidestep. Given the reset on
providing forward guidance, there may be some announcement regarding
eliminating future summaries as part of the reform of Fed communication. There
could be some early decisions in the works. There may also be some hints about
plans to reduce the Feds holdings of US treasuries and agency mortgage-backed
securities while maintaining sufficient reserves. Warsh has previously said he
anticipates some of his five reform working groups to report their findings and
recommendations by the end of the year, of which communications and balance
sheet policy are part.
Asia-Pacific Preview
China Industrial Production, Retail Sales Up Next
By Brian Jackson, Econoday Economist
Chinas monthly activity data for August will be the focus
in the Asia-Pacific region in the week ahead. Last months data showed weaker
growth in industrial production and a bigger decline in investment spending,
with officials noting the impact of a complex and volatile external
environment. Official PMI survey data for August published late last month
showed contraction in both the manufacturing and services sectors, suggesting
that the data in the week ahead may show subdued conditions. The data will also
be accompanied by officials updated assessment of conditions and policy
settings.
Taiwan's central bank will hold its quarterly policy meeting
in the week ahead. The main policy rate has been left on hold at 2.00 percent
for more than two years, but two of the fifteen board members supported an
increase of 12.5 basis points at the previous meeting in June. Strong
AI-related demand has boosted exports and industrial production this year and
higher fuel prices pushed headline inflation to 2.6 percent in June, its
highest level in more than a year. The June inflation data was published after
the previous meeting and inflation has since fallen to 2.04 percent in August,
perhaps easing concerns about the impact of the Iran conflict on prices. That
may be enough to convince a majority of members to leave rates on hold again at
this meeting.
New Zealand quarterly GDP data in the week ahead will likely
show some impact of the Iran conflict on economic activity, but more timely
monthly data have alleviated concerns about the impact. At their most recent
meeting, early in the month, officials at the Reserve Bank of New Zealand
expressed confidence that economic growth has "most likely resumed but
remains uneven" and they expect that recovery to "strengthen and
broaden.
Monthly trade data will also be published. Singapore and
India will also report monthly trade data for August. Trade data already
published elsewhere in the region have shown continued strength in AI-related
demand, outweighing the impact of disrupted access to the Strait of Hormuz.
India will also report wholesale and consumer price data in
the week ahead. Headline CPI inflation has risen from 3.48 percent in April to
3.93 percent in May, 4.38 percent in June, and 4.45 percent in July, well above
the mid-point of the Reserve Bank of India's target range of two percent to six
percent. At their policy meeting held last month, officials left policy rates
on hold and revised down their headline and core inflation forecasts for the
current fiscal year. Nevertheless, they will be looking for evidence that price
pressures are moderating ahead of their next meeting in early October.
The Week Ahead: Econoday Consensus Forecasts
Monday
India CPI for August (Mon 1600 IST; Mon 1030 GMT; Mon
0630 EDT)
Consensus Forecast, Y/Y: 4.8%
Consensus Range, Y/Y: 4.7% to 4.9%
Higher fuel costs expected to lift CPI to 4.8 percent on
year in August from 4.5 percent in July.
India WPI for August (Mon 1600 IST; Mon 1030 GMT; Mon
0630 EDT)
Consensus Forecast, Y/Y: 9.9%
Consensus Range, Y/Y: 9.89% to 9.9%
Wholesale price inflation expected to stay very hot at 9.9
percent on year in August versus 9.78 percent in July.
Canada CPI for August (Mon 0830 EDT; Mon 1230 GMT)
Consensus Forecast, M/M: 0.0%
Consensus Range, M/M: 0.0% to 0.3%
Consensus Forecast, Y/Y: 3.0%
Consensus Range, Y/Y: 3.0% to 3.1%
Consensus Forecast, Core CPI - Y/Y: 2.0%
Consensus Range, Core CPI - Y/Y: 1.9% to 2.3%
Energy prices continue to underpin CPI with the overall
number expected to hold at 3.0 percent on year in August and core seen steady
at 1.9 percent too.
Canada Manufacturing Sales for July (Mon 0830 EDT; Mon
1230 GMT)
Consensus Forecast, M/M: -0.2%
Consensus Range, M/M: -0.2% to -0.2%
Forecasters agree with Stats Canadas preliminary estimate
of minus 0.2 percent.
Tuesday
China Fixed Asset Investment for August (Tue 1000
CST; Tue 0200 GMT; Mon 2200 EDT)
Consensus Forecast, Year to Date on Y/Y Basis: -7.1%
Consensus Range, Year to Date on Y/Y Basis: -7.4% to -6.6%
Another shockingly bad number expected at minus 7.1 percent
on year in August, even worse than the minus 6.7 percent in July as this keeps
getting worse.
China Industrial Production for August (Tue 1000 CST;
Tue 0200 GMT; Mon 2200 EDT)
Consensus Forecast, Y/Y: 4.85%
Consensus Range, Y/Y: 4.8% to 5.0%
The consensus sees output up 4.9 percent in August, better
than the 4.5 percent increase in July.
China Retail Sales for August (Tue 1000 CST; Tue 0200
GMT; Mon 2200 EDT)
Consensus Forecast, Y/Y: 0.8%
Consensus Range, Y/Y: 0.4% to 1.0%
Sales expected marginally better with a gain of 0.8 percent
on year in August, up from 0.6 percent
In July.
UK Labour Market Report for September (Tue 0700 BST;
Tue 0600 GMT; Tue 0200 EDT)
Consensus Forecast, ILO Unemployment Rate: 5.0%
Consensus Range, ILO Unemployment Rate: 4.9% to 5.0%
Consensus Forecast, Average Earnings - Y/Y: 3.9%
Consensus Range, Average Earnings - Y/Y: 3.9% to 4.0%
Weak job market is evident with the unemployment rate at 5.0
percent in September, up from 4.9 percent in August. Earnings growth expected
lower at 3.9 percent versus 4.1% percent in August.
France CPI for August (Tue 0845 CEST; Tue 0645 GMT; Tue
0245 EDT)
Consensus Forecast, M/M: 0.7%
Consensus Range, M/M: 0.7% to 0.7%
Consensus Forecast, Y/Y: 2.4%
Consensus Range, Y/Y: 2.4% to 2.4%
Consensus Forecast, HICP - M/M: 0.8%
Consensus Range, HICP - M/M: 0.8% to 0.8%
Consensus Forecast, HICP - Y/Y: 2.7%
Consensus Range, HICP - Y/Y: 2.7% to 2.7%
The consensus sees no revision from the flash with CPI up
0.7 percent on month and 2.4 percent on year.
Germany ZEW Survey for September (Tue 1100 CEST; Tue 0900
GMT; Tue 0500 EDT)
Consensus Forecast, Current Conditions: -53.1
Consensus Range, Current Conditions: -54.1 to -52.0
Consensus Forecast, Economic Sentiment: 40
Consensus Range, Economic Sentiment: 25.0 to 42.3
The consensus looks for an improvement in current conditions
to minus 53.1 in September from minus 61.1 in August. Economic sentiment is
also expected up to 40.0 in September from 34.2 in August.
US Empire State Manufacturing Index for September (Tue
0830 EDT; Tue 1230 GMT)
Consensus Forecast, Index: 14.1
Consensus Range, Index: -9 to 20.4
The business activity index is expected to recede to 14.1 in
September, still showing expansion, from. 20.6 in August.
Wednesday
Japan Merchandise Trade for August (Wed 0850 JST; Tue
2350 GMT; Tue 1950 EDT)
Consensus Forecast, Balance: -1,052.2 B
Consensus Range, Balance: -1,103.60 B to -920.00 B
Consensus Forecast, Imports - Y/Y: 26.0%
Consensus Range, Imports - Y/Y: 24.0% to 26.1%
Consensus Forecast, Exports - Y/Y: 17.7%
Consensus Range, Exports - Y/Y: 15.9% to 19.6%
Japanese export values are expected to post another
double-digit percentage gain for the sixth straight month on the year in August
after reaching a record high in the previous month, driven by gains in
automobiles, computer chips and semiconductor-producing equipment, continuing a
trend seen in recent months.
The weak yen was also seen to have boosted both export and
import values. Import values are expected to have risen sharply again in
August, as Japan continued to actively acquire crude oil, chipmaking equipment
and non-ferrous metals. Import values had already reached a record high in
July.
Robust oil imports amid the yens continued weakness are
expected to push the countrys trade balance into deficit for the fourth
straight month, with the shortfall seen topping 1 trillion for the first time
in seven months.
Exports are seen rising for the 12th straight month in
August, up 17.7 percent on the year after increasing 23.2 percent a month
earlier. Export values surged to 11.51 trillion in July, breaking the previous
record of 10.98 trillion reached in March 2026.
Imports are expected to rise 26.0 percent in August after
being revised up to a 27.9 percent rise in July from the initial 27.8 percent,
as robust oil imports amid lingering geopolitical tensions in the Middle East
continued to keep international prices elevated. The weak yen is also expected
to have pushed up the value of imports. In July, import values hit a record
high of 12.15 trillion, exceeding the previous high of 11.34 trillion reached
only a month earlier.
These trends in trade activity are expected to bring Japans
trade balance into deficit for a fourth straight month in August and widen the
shortfall to 1.052.2 trillion, the highest since January, from a revised
deficit of 638.34 billion a month earlier.
Japan Machinery Orders for July (Wed 0850 JST; Tue
2350 GMT; Tue 1850 EST)
Consensus Forecast, M/M: -1.0%
Consensus Range, M/M: -7.7% to 1.8%
Consensus Forecast, Y/Y: 15.3%
Consensus Range, Y/Y: 6.2% to 18.6%
Japans core machinery orders, a key leading indicator of
business investment in equipment and software, are expected to fall on the
month for the first time in two months in July.
Still, machinery orders are expected to maintain their solid
footing, with the Bank of Japans Tankan survey on capital investment plans for
fiscal 2026 indicating a solid corporate appetite for capital investment.
Recent indicators, including industrial production and machine tool orders,
have also shown positive signals, underscoring the strength in machinery order
trends.
July core orders are forecast to fall 1.0 percent on the
month after jumping 9.7 percent a month earlier. The sharp rebound in June
orders was led by non-ferrous metal producers, telecommunications equipment
makers and real-estate firms.
On an annual basis, core machinery orders are expected to
rise for the second straight month, gaining 15.3 percent in July after rising
16.9 percent in the previous month. In June, the Cabinet Office maintained its
assessment that machinery orders are showing signs of a pickup. The office
also forecast that core orders would rise a solid 4.9 percent on quarter in
July-September.
UK CPI for August (Wed 0700 BST; Wed 0600 GMT; Wed 0200
EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.2% to 0.5%
Consensus Forecast, Y/Y: 3.1%
Consensus Range, Y/Y: 2.8% to 3.1%
Consensus Forecast, Core CPI - Y/Y: 2.6%
Consensus Range, Core CPI - Y/Y: 2.6% to 2.7%
Inflation is seen picking up in August relative to July as
fuel costs rebounded. The consensus sees CPI up 0.5 percent on the month and
3.1 percent on year versus 0.3 percent and 2.9 percent, respectively, in July.
Eurozone Industrial Production for July (Wed 1100
CEST; Wed 0900 GMT; Wed 0500 EDT)
Consensus Forecast, M/M: -0.5%
Consensus Range, M/M: -0.9% to -0.2%
Consensus Forecast, Y/Y: -0.3%
Consensus Range, Y/Y: -0.5% to -0.1%
Declines expected in industrial production for July, 0.5
percent on the month, and 0.3 percent on year.
Canada Housing Starts for August (Wed 0815 EDT; Wed 1215
GMT)
Consensus Forecast, Annual Rate: 235K
Consensus Range, Annual Rate: 235K to 248K
The consensus looks for starts edging up to 235K from 229K
in July, still a sluggish showing.
US Retail Sales for August (Wed 0830 EDT; Wed 1230
GMT)
Consensus Forecast, Retail Sales - M/M: 0.8%
Consensus Range, Retail Sales - M/M: 0.2% to 1.1%
Consensus Forecast, Ex-Vehicles - M/M: 0.5%
Consensus Range, Ex-Vehicles - M/M: 0.1% to 0.6%
Consensus Forecast, Ex-Vehicles & Gas - M/M: 0.3%
Consensus Range, Ex-Vehicles & Gas - M/M: 0.1% to
0.4%
Sales expected to bounce back big time in August in part due
to rising prices, also reflecting the end of the seasonal drag linked to the
timing of the Amazon Prime sales.
US Imports and Export Prices for August (Wed 0830
EDT; Wed 1230 GMT)
Consensus Forecast, Import Prices - M/M: 0.4%
Consensus Range, Import Prices - M/M: -0.3% to 0.7%
Consensus Forecast, Import Prices - Y/Y: 6.7%
Consensus Range, Import Prices - Y/Y: 6.0% to 6.8%
Consensus Forecast, Export Prices - M/M: -0.5%
Consensus Range, Export Prices - M/M: -0.7% to 1.4%
Import prices expected up 0.4 percent, export prices down
0.5 percent on the month in August.
Italy CPI for August (Wed 1600 CEST; Wed 1400 GMT; Wed
1000 EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.5% to 0.5%
Consensus Forecast, Y/Y: 3.3%
Consensus Range, Y/Y: 3.3% to 3.3%
Consensus Forecast, HICP - M/M: 0.1%
Consensus Range, HICP - M/M: 0.1% to 0.1%
Consensus Forecast, HICP - Y/Y: 3.2%
Consensus Range, HICP - Y/Y: 3.2% to 3.2%
The consensus looks for no revision in the final from the
flash with CPI up 0.5 percent on the month and 3.3 percent on year.
US Business Inventories for July (Wed 1000 EDT; Wed
1400 GMT)
Consensus Forecast, M/M: 0.2%
Consensus Range, M/M: 0.1% to 0.3%
A fairly standard 0.2 percent increase on the month is the
call for July.
US Housing Market Index for September (Wed 1000 EDT;
Wed 1400 GMT)
Consensus Forecast, Index: 34
Consensus Range, Index: 33 to 35
Homebuilder sentiment expected to erode to 34 in September
from 35 in August.
US FOMC Announcement (Wed 1400 EDT; Wed 1800 GMT)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Federal Funds Rate - Target Range: %
Consensus Range, Federal Funds Rate - Target Range: 3.50%
to 3.75% to 3.75% to 4.0%
After the latest CPI report showed rising core inflation,
the consensus looks for a 25 basis point rate hike, perhaps as a one-off,
perhaps as the start of a tightening cycle, depending on what happens with
energy prices.
Brazil Selic Rate for September (Wed 0630 BRT; Wed 0930
GMT; Wed 0530 EDT)
Consensus Forecast, Change: -25 bp
Consensus Range, Change: -25 bp to 0 bp
Consensus Forecast, Level: 13.75%
Consensus Range, Level: 13.75% to 14.00%
The consensus looks for a 25 bp rate cut.
Thursday
New Zealand GDP for Second Quarter (Thu 1045 NZST; Wed
2245 GMT; Wed 1845 EDT)
Consensus Forecast, Q/Q: 0.1%
Consensus Range, Q/Q: -0.1% to 0.2%
Consensus Forecast, Y/Y: 2.2%
Consensus Range, Y/Y: 2.2% to 2.2%
Growth continues in New Zealand in the face of energy cost
headwinds. The consensus sees GDP up 0.1 percent in Q2 from Q1 and up a decent
2.2 percent on year. Exports, construction, and other sectors are holding up
surprisingly well.
Eurozone HICP for August (Thu 1100 CEST; Thu 0900
GMT; Thu 0500 EDT)
Consensus Forecast, HICP - M/M: 0.4%
Consensus Range, HICP - M/M: 0.2% to 0.4%
Consensus Forecast, HICP - Y/Y: 3.3%
Consensus Range, HICP - Y/Y: 3.3% to 3.3%
Consensus Forecast, Narrow Core - Y/Y: 2.4%
Consensus Range, Narrow Core - Y/Y: 2.4% to 2.4%
HICP seen up 0.4 percent on month and 3.3 percent on year.
UK BoE Announcement & Minutes (Thu 1200 BST; Thu
1100 GMT; Thu 0700 EDT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 3.75%
Consensus Range, Level: 3.75% to 3.75%
Lackluster employment market and lack of spillover inflation
from the initial energy shock leaves the BOE room to keep rates where they are.
US Housing Starts and Permits for August (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Starts - Annual Rate: 1.315 M
Consensus Range, Starts - Annual Rate: 1.250 M to 1.363
Consensus Forecast, Permits - Annual Rate: 1.405 M
Consensus Range, Permits - Annual Rate: 1.350 M to
1.425 M
Starts expected a bit better at 1.315 million unit rate in
August from 1.239 million in July with a boost from multifamily construction
while single family starts are limited by affordability issues.
US Jobless Claims for Week of September 12 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 208 K
Consensus Range, Initial Claims - Level: 190 K to 210
K
Claims are expected to hold in the same range just above
200K as the market holds steady.
US Philadelphia Fed Manufacturing Index for September (Thu
0830 EDT; Thu 1230 GMT)
Consensus Forecast, Index: 33
Consensus Range, Index: 10 to 47
Manufacturing expansion expected to remain pretty robust
with the business activity index at 33 in September versus a remarkable 47.4
in August.
US Pending Home Sales Index for August (Thu 1000 EDT;
Thu 1400 GMT)
Consensus Forecast, M/M: 0.4%
Consensus Range, M/M: -1.0% to 1.0%
The consensus looks for sales up a modest 0.4 percent on the
month in August as sales remain depressed by affordability issues.
Friday
Japan CPI for October (Fri 0830 JST; Thu 2330 GMT;
Thu 1930 EDT)
Consensus Forecast, CPI - Y/Y: 2.0%
Consensus Range, CPI - Y/Y: 1.9% to 2.1%
Consensus Forecast, Ex-Fresh Food - Y/Y: 1.8%
Consensus Range, Ex-Fresh Food - Y/Y: 1.8% to 2.0%
Consensus Forecast, Ex-Fresh Food & Energy - Y/Y:
2.0%
Consensus Range, Ex-Fresh Food & Energy - Y/Y: 1.9%
to 2.2%
Japans nationwide core consumer price index, which excludes
fresh food, is expected to remain steady in August from the previous month,
while the two other key inflation measures are expected to edge up to the Bank
of Japans 2 percent inflation target. The governments latest subsidies for
electricity and gas charges took effect during the month and may have helped
curb inflation, while the weak yen continued to boost import costs, with fresh
food prices and rents also showing signs of climbing.
The uptrend in consumer inflation is becoming clearer as
rising energy costs amid prolonged tensions in the Middle East and the yens
weakness push up import costs. Prices are also climbing as shops pass higher
labor, materials, packaging and transportation costs on to consumers amid
widespread worker shortages and elevated import costs in the resource-poor
country.
The core CPI is expected to rise 1.8 percent on the year in
August, little changed from the previous month. It accelerated from a 1.6
percent increase in June and 1.4 percent in both April and May, the lowest
level since March 2022.
The other two key consumer inflation readings are expected
to climb to the BOJs target. The total CPI is expected to rise to 2.0 percent
in August from 1.9 percent a month earlier, while the core-core CPI, which
excludes fresh food and energy, is also forecast to advance to 2.0 percent from
1.9 percent in July.
Japan Bank of Japan Announcement (Fri 1130 JST; Fri
0230 GMT; Thu 2230 EDT)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 25 bp to 25 bp
Consensus Forecast, Level: 1.25%
Consensus Range, Level: 1. 25% to 1.25%
BOJ officials are signaling they are ready to move as policy
normalization continues.
UK Retail Sales for August (Fri 0700 BST; Fri 0600 GMT;
Fri 0200 EDT)
Consensus Forecast, M/M: -0.2%
Consensus Range, M/M: -0.5% to 0.7%
Consensus Forecast, Y/Y: 1.8%
Consensus Range, Y/Y: 1.0% to 1.9%
Sales are expected down 0.2 percent on the month and up 1.8
percent on year.
Germany PPI for August (Fri 0800 CEST; Fri 0700 GMT; Fri
0200 EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.3% to 1.0%
Consensus Forecast, Y/Y: 3.9%
Consensus Range, Y/Y: 3.8% to 4.3%
PPI seen up 0.5 percent on the month in August and up 3.9
percent on year.
US Industrial Production for August (Fri 0915 EDT;
Fri 1230 GMT)
Consensus Forecast, Industrial Production - M/M: 0.3%
Consensus Range, Industrial Production - M/M: 0.0% to
0.4%
Consensus Forecast, Manufacturing Output - M/M: 0.2%
Consensus Range, Manufacturing Output - M/M: 0.1% to 0.3%
Consensus Forecast, Capacity Utilization Rate: 76.4%
Consensus Range, Capacity Utilization Rate: 76.3% to 76.6%
A moderate 0.3 percent rise on the month is the call with
capacity usage up to 76.4 percent from 76.3 percent in July.
US Leading Indicators for August (Fri 0915 EDT; Fri 1230
GMT)
Consensus Forecast, M/M: 0.2%
Consensus Range, M/M: 0.1% to 0.2%
LEI expected up 0.2 percent on the month in August, same as
in July.
|